
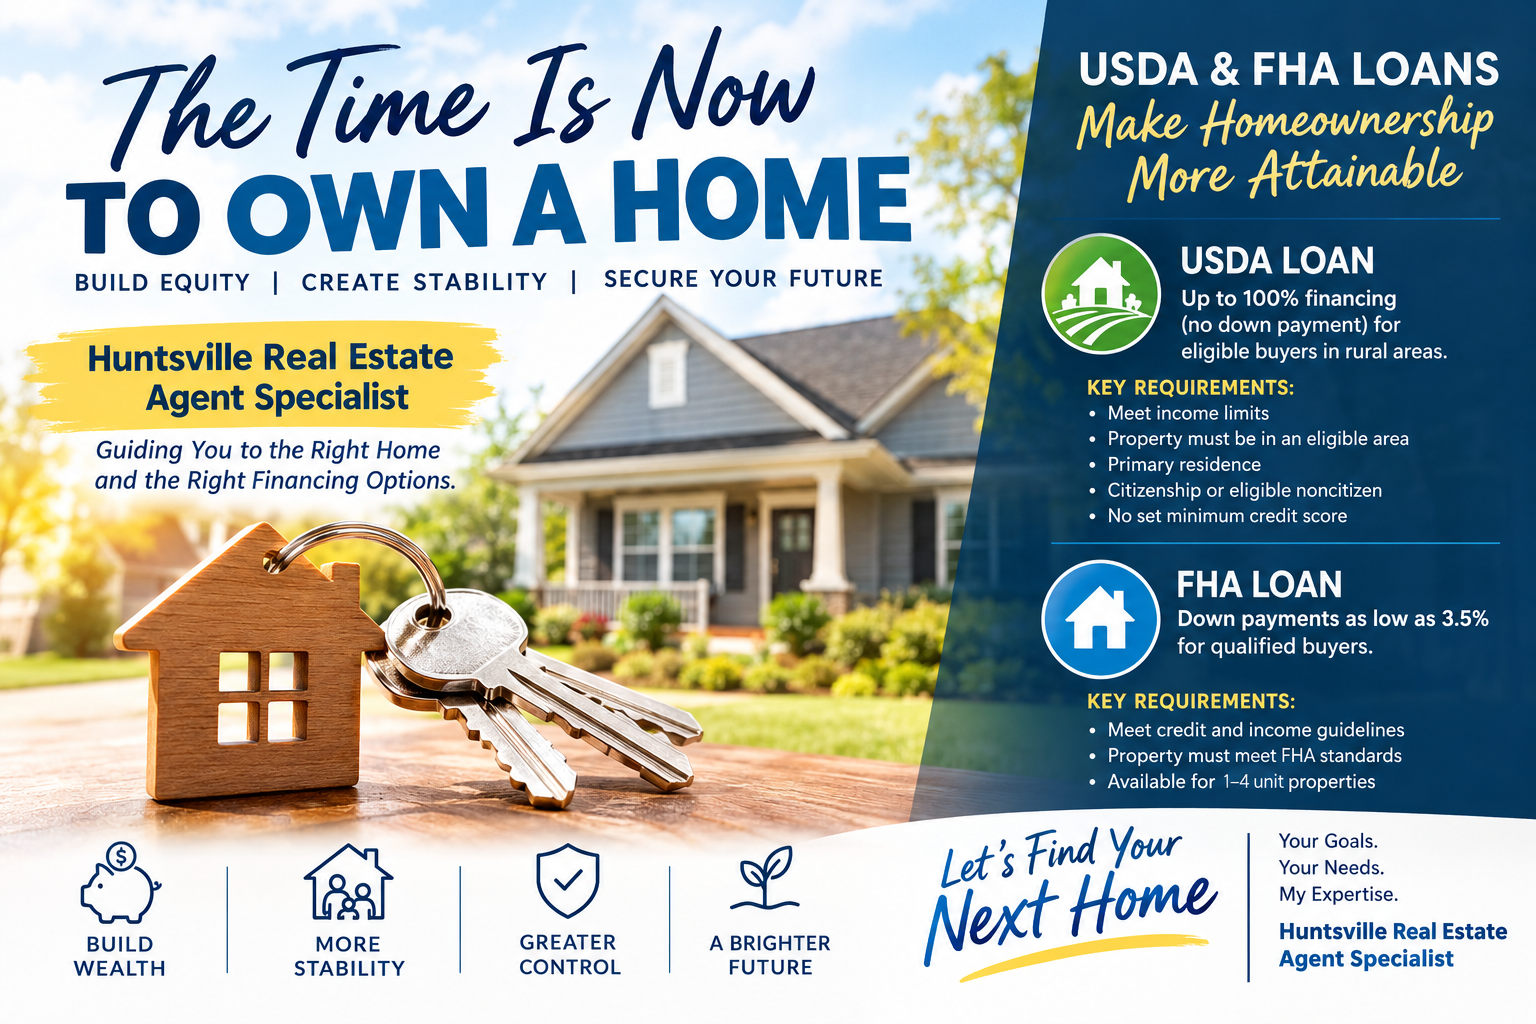
Owning a home is more than having a place to live. It is an opportunity to build stability, create long-term wealth, and put your monthly housing payment toward something you own. For many people who are currently renting, the question is no longer simply whether they can afford a home. The more important question may be whether they are financially prepared to take advantage of the homeownership opportunities available to them now.
Working with a Huntsville real estate agent specialist can help buyers understand those opportunities and determine which path may fit their income, credit profile, financial goals, and desired property. Homeownership does not require every buyer to have a huge down payment or perfect credit. Programs such as USDA and FHA financing can make purchasing a home more attainable for qualified buyers.
Why the Time Is Now to Consider Homeownership
Renting provides flexibility, but it does not create ownership. Every month, a renter makes a housing payment without building equity in the property. A homeowner, on the other hand, can gradually build equity as the mortgage balance is reduced and the property potentially increases in value over time.
Homeownership can also provide greater control over your living situation. Instead of being subject to a landlord’s decisions, a homeowner can make improvements, personalize the property, and plan around a home that belongs to them.
Waiting for the “perfect” market can also become a reason to postpone homeownership indefinitely. Mortgage rates, home prices, inventory, and individual financial circumstances can change. There is no guarantee that waiting will produce a better opportunity. A stronger strategy is to understand your financing options today, determine what you can comfortably afford, and make a decision based on your personal financial position.
That does not mean rushing into a purchase. It means becoming prepared now.
USDA Home Loans and the Possibility of Zero Down Payment
One of the most important programs for qualified buyers is the USDA Single Family Housing Guaranteed Loan Program. USDA states that eligible applicants may receive 100% financing, meaning a qualifying buyer may be able to purchase a home with no down payment. The program is designed for low- and moderate-income households purchasing a primary residence in an eligible rural area.
The USDA Guaranteed program generally requires the household to meet applicable income limits, occupy the property as the primary residence, and meet citizenship or eligible noncitizen requirements. The property must also be located in an area that meets USDA’s eligibility requirements. USDA’s eligibility system allows buyers and lenders to check whether a particular property location qualifies.
Another important point is that USDA does not establish a universal minimum credit score for its Guaranteed program. Instead, applicants must demonstrate a willingness and ability to manage and repay debt, while the approved lender evaluates the overall application.
For eligible buyers, this can change the conversation completely. Instead of assuming that a home purchase requires tens of thousands of dollars saved for a down payment, it may be possible to explore a zero-down-payment USDA option.
However, zero down payment does not necessarily mean zero money is needed. Buyers may still have expenses associated with inspections, closing, prepaid items, earnest money, moving, insurance, and other costs depending on the transaction and financing structure. A lender can explain which costs may be financed, covered through assistance, paid by the buyer, or addressed through other permitted arrangements.
FHA Financing Can Also Help Buyers Move Forward
FHA financing is another major option for homebuyers, particularly those who may not have a large down payment. HUD states that FHA-insured mortgages can offer down payments as low as 3.5% for qualified borrowers. FHA loans are available for eligible one- to four-unit properties, subject to FHA requirements.
The 3.5% figure is important because it can make homeownership more realistic for someone who has steady income but has not accumulated a large amount of cash. FHA also has credit requirements that differ from conventional financing, and HUD notes that FHA can have lower minimum credit-score requirements than many conventional loans.
For buyers considering FHA, the lender will review income, employment, credit history, debts, assets, and the property itself. The home must also meet FHA property requirements related to safety, soundness, and livability.
The right financing program depends on the buyer. USDA may be attractive for an eligible buyer seeking 100% financing, while FHA may be a better fit for someone purchasing a property that does not qualify for USDA or whose circumstances make FHA more appropriate.
What You May Need to Prepare
Before beginning the home search, buyers should prepare their financial information. A lender will typically need documentation that allows them to evaluate income, employment, debts, credit, and available assets.
Depending on the lender and loan program, buyers may need recent pay stubs, W-2 forms, tax returns when applicable, bank statements, identification, employment information, information about existing debts, and documentation explaining deposits or other financial activity.
It is also important to review your credit before applying. Paying bills on time, avoiding unnecessary new debt, keeping credit balances under control, and correcting inaccurate information can strengthen your overall financial position.
Your debt-to-income ratio is another important consideration. A buyer may qualify for a particular loan amount but still need to determine whether that payment comfortably fits into the household budget. Homeownership involves more than the mortgage. Buyers should account for property taxes, homeowners insurance, utilities, maintenance, repairs, and potential homeowners association expenses.
The Goal Is Not Just to Buy—It Is to Buy Wisely
The purpose of working with a Huntsville real estate agent specialist is not simply to get a buyer into a house as quickly as possible. The goal should be to help the buyer understand the process, identify appropriate properties, evaluate the numbers, negotiate effectively, and move toward a purchase that makes financial sense.
A good home purchase should fit the buyer’s lifestyle and long-term plans. The right property should be affordable today while also giving the homeowner room to handle normal ownership expenses.
Buyers should also remember that loan programs and eligibility requirements can change. USDA income limits and property eligibility are determined according to program rules, while FHA requirements are governed by HUD and participating lenders. Final approval always comes from the lender or applicable government program—not from a real estate agent.
The Time Is Now to Get Prepared
You do not have to wait until you have everything figured out before taking the first step. Getting pre-qualified or pre-approved, reviewing your credit, understanding your purchasing power, and learning whether you may qualify for USDA, FHA, or another financing option can give you a clearer picture of what is possible.
The time is now because preparation creates options. If you qualify for a zero-down USDA loan, you should know it. If FHA financing makes more sense, you should understand it. If you need to improve your credit or reduce debt before buying, knowing that early gives you a plan.
Homeownership is not simply about buying a house. It is about creating a place of your own and potentially building equity over time instead of continuing to spend indefinitely on rent.
If owning a home has been a goal, this is the time to stop assuming that it is out of reach and start finding out what you may actually qualify for.
Verenetta Johnson | Huntsville Real Estate Agent & Relocation Specialist

The Time Is Now! NO DOWNPAYMENT for your DREAM HOUSE in Huntsville, Alabama!!!
🌐 https://northalabamarealestate.blog/
📞 Call/Text: +1 256.653.8881
📧 Email: verenetta@gmail.com
Dees Realty Group
470 Providence Main Street Ste 202J
Huntsville, AL 35806
Leave a Reply